IFI valuation.
Market value at 1 January, reasoned and defensible.
The declared value and its justification
The real estate wealth tax (IFI) is declared on the market value of properties at 1 January of the tax year. A value that is too high costs tax every year; an insufficiently reasoned value exposes you to reassessment and late-payment interest. In the event of an audit, it is the justification that counts.
Our IFI reports establish the market value using the methods of the French Property Valuation Charter, supported by comparables, and reason each allowance adopted: the statutory 30% on the main residence, occupation or letting discounts; the joint-ownership discount is the one most often challenged.
The joint-ownership discount, in the glossaryFirst declaration
Becoming liable to IFI, a significant acquisition, returning from abroad: setting a solid starting value avoids years of discussion.
Properties without a readable market
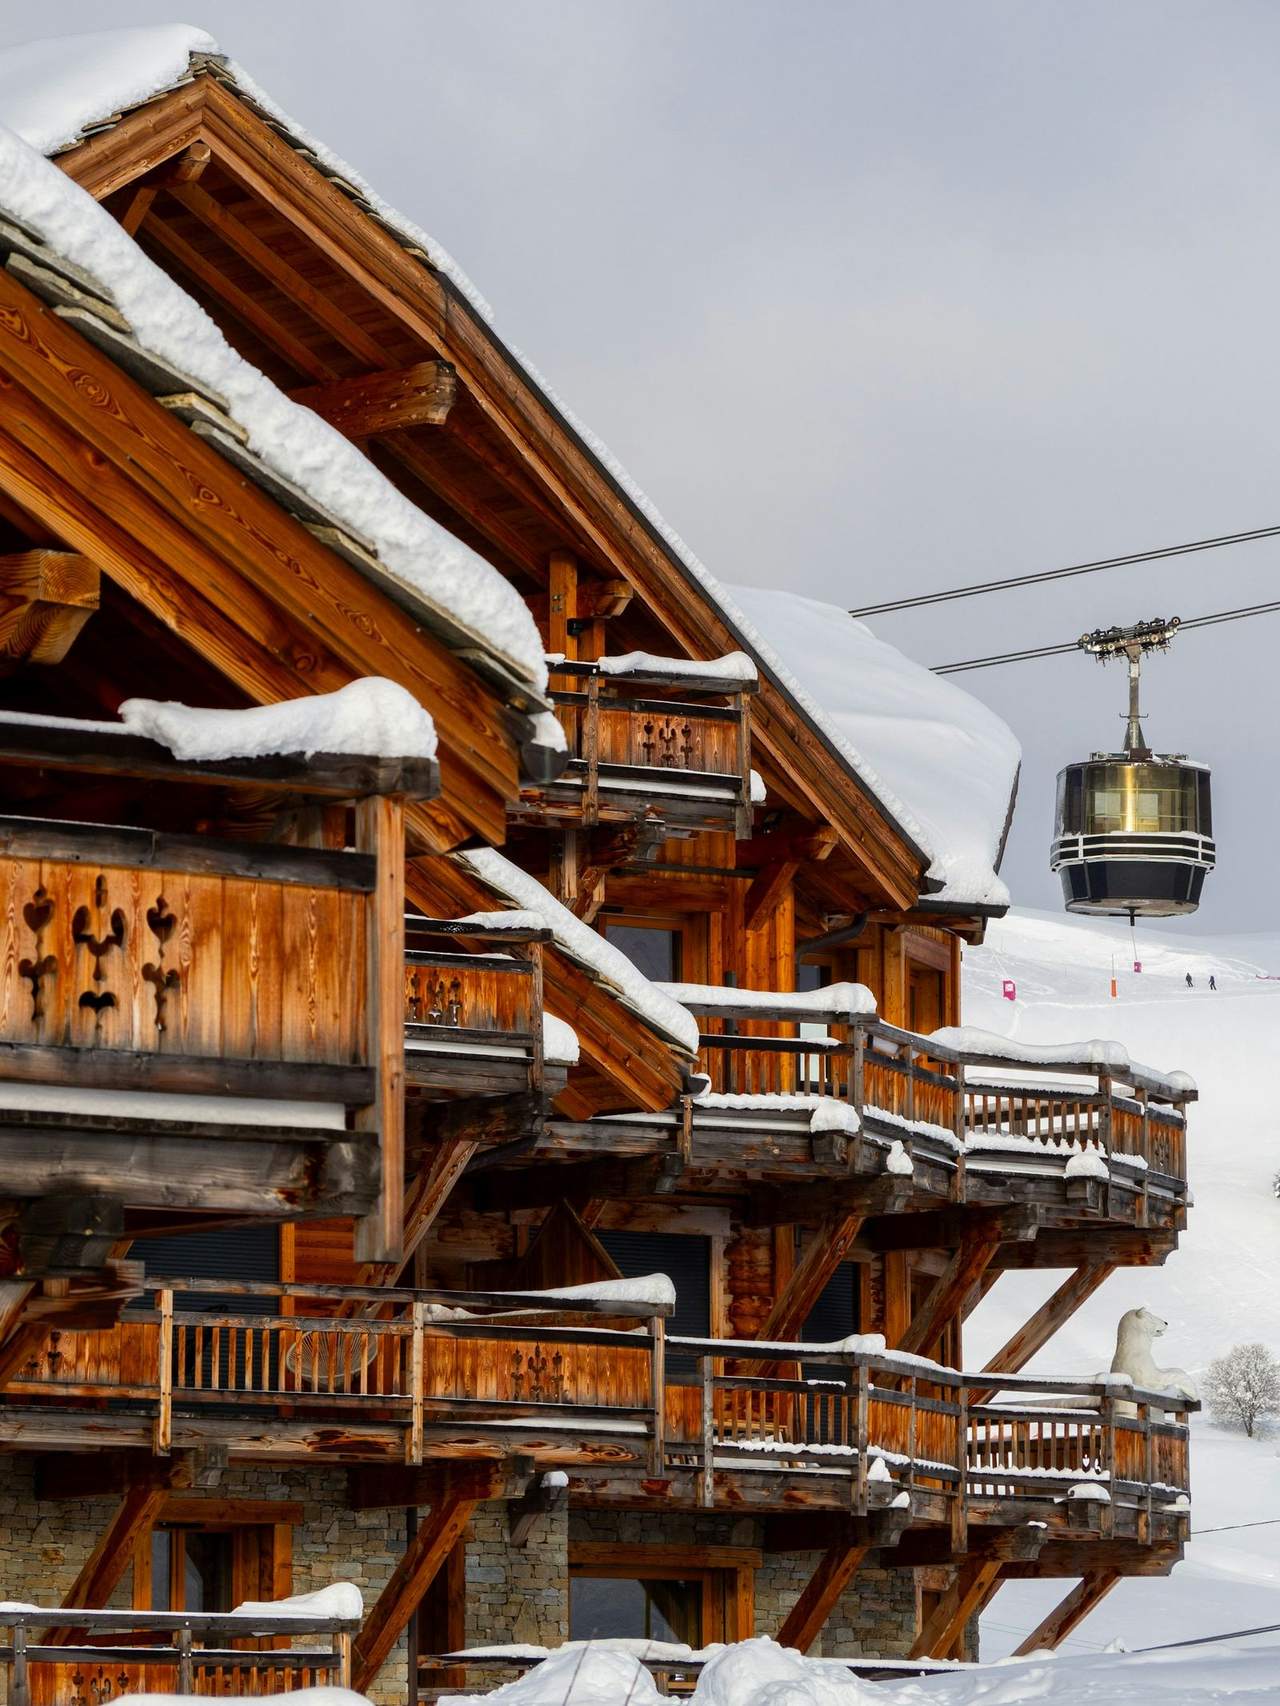
Resort chalets, private mansions, atypical or jointly owned properties: where public databases say nothing, the valuation report establishes the value.
Audit or reassessment
Response to a proposed reassessment, litigation: a reasoned, defensible counter-value, established by an independent firm.
Private banks, family offices, notaries.
We act at the direct request of taxpayers as well as on the recommendation of their advisers (private bankers, notaries, tax lawyers), throughout France and for properties held in Monaco by French tax residents. Each report is signed by the valuer who answers for it.
What we are really asked.
Three families of allowances are commonly accepted: the statutory 30% on the main residence, an occupation discount when the property is let, and the joint-ownership discount when only a share is held. Apart from the first, none is automatic: their rate must be justified property by property, and that is precisely the purpose of a valuation report.
Through a proposed reassessment based on comparable transactions, generally taken from transaction databases. The effective response is not to argue over each comparable, but to set against it a complete, reasoned valuation: explicit methods, relevant comparables, documented allowances. That is what an independent valuation report provides.
Fees depend on the time spent: nature and number of properties, legal complexity (joint ownership, split ownership), available documentation. They are set by quote before the assignment, and bear no comparison with the annual cost of a poorly calibrated value, in either direction.
Prepare your declaration.
Describe your property and your situation, in complete confidence. The valuer who replies is the one who will sign the report.
Request a valuation